Thinking of buying land or a house in Kenya? Check the seller, the title, the search, the rates and the boundaries before you pay a deposit. Here is the full pre-deposit checklist.
Before You Pay a Deposit: What Every Kenyan Property Buyer Must Check First
Most property disasters in Kenya do not begin at the land registry. They begin the moment a buyer pays a deposit too early. A bank transfer, an M-Pesa “booking fee” or a cash handover to an agent feels harmless. Then the buyer discovers the seller does not own the land, the title is charged to a bank, or the same plot was sold to three other people.
Recovering money after the fact is slow, expensive and uncertain. Checking first is cheap and quick. This guide sets out what to check before you pay a deposit on property in Kenya, so you can protect your money from the very start.
Why the Deposit Is the Point of No Return
A deposit signals commitment. Once it leaves your account, you have less bargaining power, and you may be tied to an agreement whose terms you did not fully read. If the seller turns out to have no right to sell, you are left chasing someone who may be hard to find.
The rule is simple: do not pay anything until the checks below are done and an advocate has reviewed the paperwork. That includes “booking fees”, “reservation fees” and “processing fees”.
Check 1: Is the Seller Really the Owner?
Ask the seller for:
- A copy of the title deed or lease.
- Their national ID or passport, and KRA PIN.
- If the seller is a company, the certificate of incorporation, a CR12 showing the directors, and a board resolution authorising the sale.
- If someone is selling on the owner’s behalf, a registered power of attorney.
The name on the ID must match the name on the title. If the owner has died, the property can only be sold by someone holding a grant of letters of administration or a confirmed grant. A family member saying “it’s ours now” is not enough.
Be wary of sellers who avoid meeting in person, change their story, or insist that the payment go to a personal account.
Check 2: Has an Official Search Been Done?
An official search at the land registry, or through the government’s online land system, is the most important check you can make. It shows the registered owner, the size and type of the title, and whether the property is charged, restricted or subject to a court order or caution.
Never rely on a photocopy of a title or on a search someone else did months ago. The register can change in a matter of days, and fraudsters rely on buyers skipping this step. Ask your advocate to carry out a fresh search before you commit.
Check 3: Is the Property Charged to a Bank or Under a Dispute?
A property can be perfectly owned and still impossible to sell cleanly. Look for:
- A charge to a bank or lender. The lender’s consent and a discharge are needed before the title can pass to you.
- Cautions and restrictions. These show that another person is claiming an interest, such as a spouse, a family member or a previous buyer.
- Court orders or pending cases. A property under litigation can be frozen.
- Auction or attachment notices, which suggest the owner is in financial difficulty.
If any of these appear, stop and take advice. Some can be resolved before completion. Others are a reason to walk away.
Check 4: Does the Land on the Ground Match the Title?
Many buyers are shown a beautiful plot, a genuine title and a pleasant seller, and still buy the wrong land. The title may describe a different parcel, or a neighbour may have built across the boundary.
- Visit the site in person, ideally with a licensed surveyor.
- Ask the surveyor to confirm the beacons and compare them with the deed plan.
- Check for encroachments, road reserves, riparian land and wayleaves such as power lines and pipelines.
- Confirm that the access road is legal and permanent, not merely a path across someone else’s land.
For a few thousand shillings, a survey can save you from a boundary dispute that lasts years.
Check 5: Are Rates, Rent and Other Charges Paid?
Unpaid county rates and land rent do not disappear when a property is sold. They can block the transfer, and in some cases the buyer ends up dealing with the arrears. Ask the seller to provide clearance certificates, and make sure the agreement states who pays charges up to completion.
For apartments and gated communities, also ask about service charges, sinking funds and any outstanding management fees.
Check 6: Is the Development Approved and the Use Allowed?
If you are buying a house, an apartment or a building under construction, check:
- Approved building plans from the county.
- A certificate of occupation or completion, where applicable.
- Zoning rules, to make sure the property can be used the way you intend, for example for residential, commercial or rental use.
- Environmental approvals, for larger developments.
Buying a property that was built without approval can leave you facing fines, demolition orders or difficulty obtaining a loan against it.
Check 7: Is Consent Needed to Sell?
Some transactions need third-party consent to be valid:
- Agricultural land in a controlled area: the Land Control Board must consent, and the application must be made within six months of the agreement. Without it, the sale can be void.
- Matrimonial property: a spouse may need to consent.
- Charged property: the lender’s consent may be needed.
- Leasehold property: the lessor may need to approve a transfer.
Ask your advocate which consents apply to your transaction, and build them into the timetable.
Check 8: Who Is the Agent, and Who Are You Paying?
If you are dealing through an agent or developer:
- Ask for their registration and licence details, and confirm them.
- Ask for the developer’s company documents and the status of the title for the whole development, including whether each unit will receive its own title.
- Be cautious of off-plan sales where the seller cannot show you the title or the approvals.
- Never pay into a personal M-Pesa number or personal bank account. Payments should go through your advocate’s client account, or to a properly named company account that your advocate has verified.
Check 9: Is the Price Fair?
A price far below the market is a red flag, not a bargain. Compare the price with similar listings nearby, and consider getting an independent valuation, particularly if you are borrowing. A bank valuation protects the lender, not you, so a separate valuation may still be worthwhile for larger purchases.
Also remember that stamp duty is calculated on the higher of the price you agree and the government’s valuation. Budget for it from the start.
Check 10: Have You Read the Sale Agreement Properly?
Do not sign a sale agreement, a letter of offer or a “temporary agreement” without legal review. These documents can bind you to deadlines, penalties and forfeiture of your deposit if you fail to complete on time. Look at:
- The purchase price and how it is paid.
- The deposit amount, and where it is held.
- The completion date, and what happens if either side is late.
- The seller’s obligations to deliver documents, clearances and vacant possession.
- Your right to a refund if the title turns out to be defective.
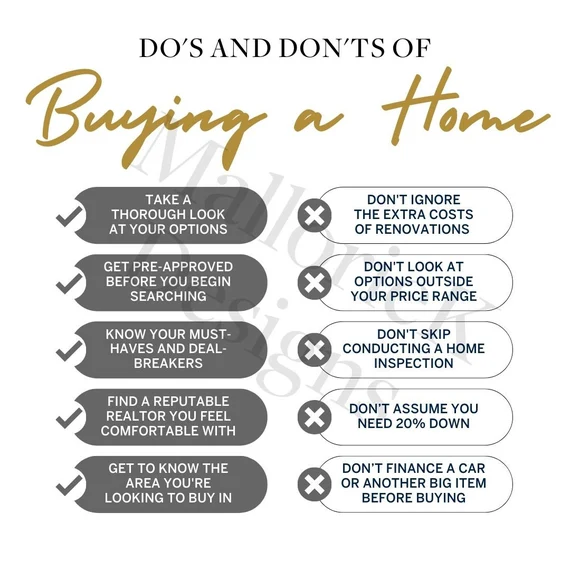
A Simple Pre-Deposit Checklist
Before you pay anything, make sure you can answer “yes” to each of these:
- Have I met the seller, and does their ID match the title?
- Has an advocate done a fresh official search?
- Is the property free of charges, cautions and court orders?
- Has a surveyor confirmed the boundaries and access?
- Are rates and land rent cleared?
- Are plans and approvals in place for any building?
- Do any consents apply, such as the Land Control Board?
- Have I verified the agent or developer?
- Is the price in line with the market?
- Has an advocate reviewed the agreement?
- Is the deposit going to an advocate’s client account?
If any answer is “no”, pause and resolve it first.
How N.M. Kamwendwa & Co. Advocates Can Help
N.M. Kamwendwa & Co. Advocates is a Kenyan law firm with offices in Nairobi and Kitui. Before you pay a deposit, the firm can assist with:
- Official searches and due diligence on the title, the seller and the property.
- Reviewing or drafting the sale agreement, so that your deposit, completion date and remedies are protected.
- Holding your deposit in a client account until the conditions of the agreement are met.
- Conveyancing, including Land Control Board consents, stamp duty and registration of the transfer.
- Advice on mortgages and charges if you are borrowing.
- Commissioner for Oaths services for affidavits and the witnessing of documents.
- Dispute resolution, if a problem arises over title, boundaries or a failed sale.
Speaking to an advocate before you pay is the most cost-effective legal decision you can make in a property purchase.
Frequently Asked Questions
Is it safe to pay a booking fee to an agent?
Treat booking fees with caution. Pay only after an advocate has verified the property and the agent, and pay through a traceable, documented channel, ideally an advocate’s client account.
How much deposit is normal when buying property in Kenya?
Many transactions use a deposit of around 10% of the price, with the balance paid on completion, but this is negotiable and should be set out in the agreement.
Can I get my deposit back if the title turns out to be fake?
You should be able to, but recovery depends on the agreement, on who holds the money and on whether the seller can be found. This is why the deposit should be held by an advocate and not paid to the seller or agent.
How long does an official search take?
It is often done within a day or two, though timing depends on the registry and system availability. It is a very small delay compared with the risk it removes.
Do I need an advocate if the property is being sold by a reputable developer?
Yes. A developer’s own advocate acts for the developer. You should have your own advocate to protect your interests.
Conclusion
A deposit is easy to pay and hard to recover. Before you part with any money, confirm who the seller is, what the register says, what the land looks like on the ground, and what the agreement actually commits you to. Do those things in the right order and you remove most of the risk from buying property in Kenya.
About to make an offer on a property? Speak to N.M. Kamwendwa & Co. Advocates before you pay. Call 0720 762001 or 0728 078289, email kamwendwanicholas@yahoo.com, or visit nmk.co.ke.
This article is for general information and does not replace legal advice on your particular transaction.